
Witness statements can add context to a crash injury claim without establishing a diagnosis. Learn which details to preserve, how to handle conflicting accounts, and why small omissions matter.

Another driver may admit an error, receive a citation, or appear to have caused the collision. Those facts can matter, but the claim still requires accurate evidence about the event, the conduct of everyone involved, the resulting injury or property loss, and applicable coverage.
A driver’s early belief about fault should guide preservation questions, not replace a complete investigation of both drivers’ conduct, the collision sequence, injury cause, and insurance.
Address safety and required crash duties
Call emergency services when needed, avoid traffic and other hazards, follow responder directions, and obtain appropriate medical care. G.S. 20-166 addresses stopping, remaining, information, assistance, vehicle movement, and other identified duties after a crash.
Preserve objective event evidence
- Road geometry, lanes, controls, visibility, weather, lighting, surface, construction, and obstructions
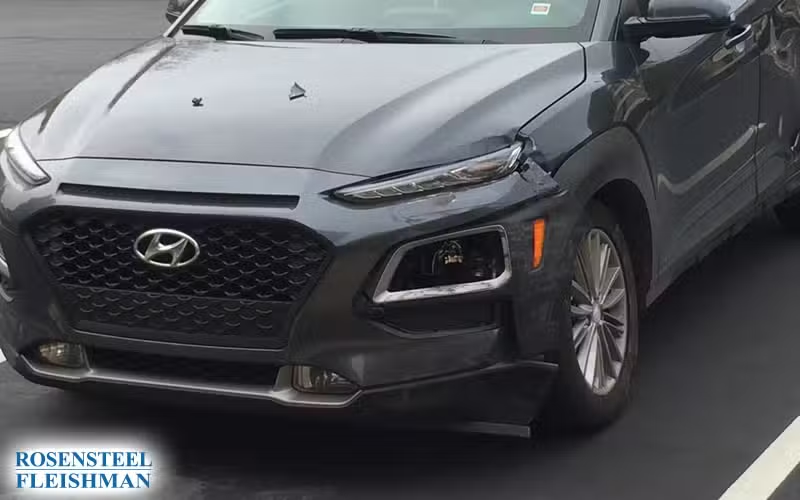
- Vehicle positions, every side of each vehicle, damage, transfer, intrusion, debris, fluid, and marks
- Traffic, business, residential, transit, dash-camera, and onboard video
- Witness identity, observation position, attention, obstructions, and exact account
- Vehicle, navigation, device, telematics, and driver-assistance data obtained and preserved lawfully
Separate fault indicators from the civil analysis
A citation, report diagram, admission, insurer opinion, rear-impact location, or traffic rule may support one issue without resolving all issues. Identify each participant’s movement, opportunity to perceive, response, and claimed conduct. Preserve contrary evidence rather than dismissing it.
Document the injured person’s conduct too
The North Carolina Department of Insurance accident guidance explains that an adjuster will investigate responsibility and notes the importance of contributory conduct in North Carolina. Record speed, lane, lighting, restraints, attention, avoidance, statements, and other facts accurately.
Confirm everyone’s identity and role
- Driver, owner, passenger, witness, employer, and involved company
- Vehicle, plate, vehicle identification, rental or fleet status, and permission
- Insurer, policy number as shown, claim number, adjuster, and written coverage position
- Police, fire, emergency medical, tow, storage, repair, and roadway agencies
Open the correct insurance tracks
Notify the relevant first-party insurer under the policy terms and identify the other party’s carrier. Review liability, collision, medical payments, uninsured or underinsured motorist, rental, umbrella, employer, household, and other possible coverage. Keep property and injury files separate.
Build medical and property chronologies
- Symptom onset, care, diagnoses, testing, treatment, restrictions, prior baseline, and later changes
- Itemized medical charges, payer records, payments, adjustments, balances, and repayment interests
- Work duties, missed time, earnings, accommodation, and return attempts
- Towing, storage, estimates, repairs, total-loss valuation, rental, and personal property
- Concrete changes in mobility, sleep, household work, care, and daily function
Communicate without overstatement
Distinguish personal observation, another person’s statement, a record, and an inference. Avoid guessing about speed, distance, diagnosis, prognosis, prior history, or future loss. Keep original communications and confirm material discussions in writing.
Review consequential documents
Identify the scope of any recorded statement, authorization, vehicle release, property settlement, injury release, sworn form, or confidentiality term. A payment for one claim should not be assumed to preserve or resolve another; read the actual language.
Calendar legal time independently
G.S. 1-52 lists three-year periods for several actions and specified accrual language. Other claims and circumstances can involve other rules. Do not assume that clear fault or an open claim extends a filing period.
The related first-hours crash guide supplies a safety, reporting, evidence, insurance, and 72-hour follow-up sequence.
Rosensteel Fleishman Car Accident & Injury Lawyers provides information about Charlotte car accident claims when another driver appears responsible.
Sources
Additional Car Accidents Articles
How Injury Severity Affects Charlotte Dooring Accident Claims
Injury severity can change the losses involved in a dooring claim, but it does not establish fault or determine a payment by itself. Clear records help connect the incident to its practical consequences.
Does Minor Vehicle Damage Always Mean Minor Injuries?
A small repair bill does not explain every consequence of a crash. Keep vehicle evidence separate from injury records, and document changes to work and daily responsibilities without guessing about their cause.
Who Pays for Ongoing Care After a Crash With Multiple Drivers in Charlotte?
Payment for current care and responsibility for crash damages are separate questions. When several drivers are involved, coverage details, evidence, and unresolved expenses all matter.




