A rental bill shows the charges; a repair timeline explains the dates. Keep approval messages and shop updates together to address the particular days or fees in dispute.
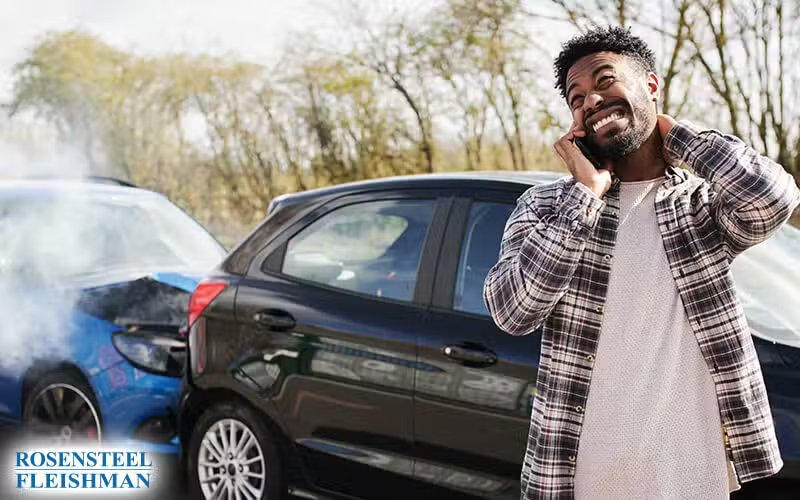

Sorting out a multicar insurance claim starts with separating what each person observed from what they concluded about responsibility. After a chain reaction crash in Charlotte, the practical question is how to address conflicting stories when several insurance policies may apply. Start with a documented sequence of impacts, then ask each insurer to identify which part of that sequence and which coverage question remain disputed.
Accountability Starts With a Clear Record
In a chain reaction crash, two questions need separate attention: what happened between the vehicles, and what each policy may cover. An insurer’s request for more evidence about an impact is different from a decision that a policy does not cover a particular loss. Keeping those issues separate helps you ask for a specific explanation instead of accepting a general statement that another insurer should handle everything.
A useful question to bring to car accident lawyers, including Rosensteel Fleishman Law Firm, is which disputed event each insurer relies on when explaining its position. A timeline, copies of statements, and a record of insurer responses give that question a concrete starting point.
Overview
- Separate the order of impacts from assumptions about fault.
- Track each policy and claim independently.
- Request written explanations for unresolved payment questions.
Document the Sequence Before Assigning Responsibility
A disagreement about who caused the crash may begin with a narrower disagreement about which contact happened first. In a hypothetical three vehicle collision, the middle driver might report being pushed into the front vehicle, while the rear driver believes the first two vehicles had already collided. Those accounts raise different questions about the sequence; neither should be treated as established merely because someone repeated it first.
Write down what you personally saw, heard, or felt, while distinguishing those observations from information supplied by others. If you heard an impact before feeling contact but could not see the vehicles behind you, preserve that distinction. Do not fill an unseen interval with a confident explanation just to make the account sound complete.
Organize available photographs, video, witness contact information, and crash documents around the disputed event. A photograph of the vehicles’ final positions should not be described as though it records their earlier movement. Likewise, a witness who saw only the final contact may have useful information without being able to explain the entire collision.
If an earlier statement contains an error, identify the exact passage and provide a dated clarification explaining the change. Keep the original and the correction together. This makes the record easier to follow without concealing uncertainty or suggesting that every participant must remember the same details.
Keep Each Insurance File Distinct
When several policies are involved, treat each claim as a separate file connected to one shared evidence record. Do not assume that sending a document to one adjuster means every other insurer has received it. Keep a delivery record so you can distinguish missing information from disagreement about information already supplied.
A compact claim log can keep repeated requests and conflicting responses manageable. Use the same vehicle labels and impact descriptions throughout, rather than changing terminology between conversations.
- Insurer, insured vehicle, claim number, and contact person
- Coverage being considered and questions still open
- Documents submitted and dates sent
- Written positions on disputed impacts or expenses
- Payments, offers, and unanswered requests
Ask each adjuster whether the unresolved issue concerns responsibility, available coverage, the amount of a loss, or missing documentation. If an adjuster directs you to another insurer, ask for the reason in writing and record which expense the referral concerns. A referral alone does not tell you whether the other insurer has accepted the claim.
Also ask which policy terms, limits, or deductibles the insurer considers relevant to the requested payment. More policies do not automatically mean every policy applies to every expense. The useful task is to identify each potential source of payment and its unresolved conditions, not to assume that the policies form one combined fund.
Connect Each Expense to the Disputed Decision
A disagreement about impact order can leave practical expenses unresolved while insurers review their positions. Keep repair estimates, towing invoices, transportation receipts, and records supporting any claimed work loss organized by date and purpose. These records explain what you are requesting even when responsibility remains disputed.
Separate whether an expense occurred from whether an insurer agrees to pay it. For example, in a hypothetical claim, an adjuster might acknowledge a repair estimate but dispute whether all listed damage belongs to the collision under review. Ask which entries are disputed and what information would address that concern instead of repeatedly resending the entire file without explanation.
Track payments alongside unpaid amounts so the same invoice does not appear as fully outstanding in multiple files. Ask what each payment covers, whether any deductions apply, and whether the insurer identifies reimbursement or coordination issues involving another policy. Keep those answers with the payment record rather than relying on a conversation you may later struggle to reconstruct.
If a car accident settlement attorney is reviewing a proposed resolution, provide the offer, any accompanying release, and the status of the other claims together. The question is not just the dollar amount, but which losses, people, and claims the documents address and what remains unresolved.
Ask for the Reason Behind Each Decision
Before responding to a disputed claim decision, identify the exact point that needs an answer. If an auto injury lawyer is reviewing conflicting insurer responses, a short comparison of their stated reasons is more useful than a folder of unlabeled correspondence.
Prepare that comparison using each insurer’s own wording, the affected expense, and the evidence you believe addresses the concern. Ask whether the response is a request for information, a partial payment decision, or a denial. Keep any stated response instructions with the letter, and request clarification when those instructions are unclear.
If an insurer has denied the claim, understanding what to review before challenging a denial can help you focus on the actual reason rather than repeat the full crash account. Your next step should connect one unresolved question to the relevant record. You do not have to make every account agree to explain clearly what you know and what still needs a decision.
Additional Car Accidents Articles
How an Uncertain Medical Prognosis Affects Serious Crash Claims in Charlotte
An uncertain medical outlook can leave important parts of a crash claim unresolved. Clear records help distinguish existing losses, household disruptions, and future questions without turning estimates into facts.
Contact Details to Collect at a Charlotte Crash Before Witnesses Leave
A witness’s name is only part of a useful record. Collect a reliable contact method, clarify what the person observed, and keep their information connected to your crash documentation.
How Moving a Vehicle After a Crash Affects Scene Evidence
Moving a vehicle changes the scene, but it does not erase every useful record. Clear timing, accurate photo labels, and firsthand accounts help distinguish original positions from later ones.