Home access expenses need more than receipts. A useful claim file connects each proposed change to a documented household difficulty while keeping cost questions separate from disputed responsibility for the collision.
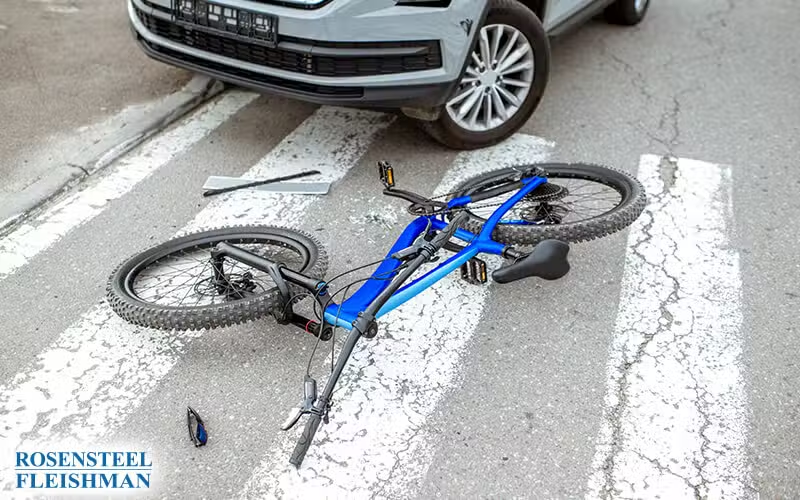

An initial bicycle accident claim may need additional records when documented injury information or its financial effects change. For a Charlotte household balancing missed work, childcare, and bills, the practical question is how to keep the insurance file accurate without treating every new expense as an expected payment.
Start With What Has Changed
When new information arrives after a bicycle accident, separate corrections to the original claim from later developments. Prepare a dated written update, identify the supporting records, and ask the insurer how to submit them. Keep the household budget separate from any anticipated settlement because coverage limits and unresolved disputes may leave some expenses unpaid.
Keep the Family Record Clear
Keep claim paperwork, receipts, and family notes in one shared file so later updates do not create conflicting versions of the same event. Personal notes should describe what happened and what changed without assigning a diagnosis or assuming an expense is covered.
Overview
- Separate new information from corrections to earlier statements.
- Connect each claimed expense to a dated supporting record.
- Confirm receipt and ask what remains under review.
- Distinguish documented losses from available insurance coverage.
Build an Update the Insurer Can Follow
A useful update explains what is different, when the information became available, and which documents support it. Include the claim number and distinguish the date of the underlying event from the date you received the record. For example, a bill received this month may describe an appointment that occurred earlier.
Separate a correction from a later development. If an earlier submission listed the wrong number of missed workdays, identify the error and provide the corrected information rather than silently replacing the old document. If additional workdays were missed afterward, describe them as a new period and attach the relevant employer or pay records.
When medical records contain new information, identify the document and its date rather than interpreting it yourself. Use the wording in the record accurately, and distinguish it from your own observations about daily activities. A personal account can describe practical effects, but it should not be presented as proof of a diagnosis or the cause of a medical condition.
Keep a running expense record that separates amounts billed, amounts paid, and balances still outstanding. Attach receipts or statements where available, and mark uncertain amounts as unconfirmed. This helps avoid counting the same charge twice or presenting an estimate as an actual expense.
In a hypothetical example, a parent initially reports two missed shifts and later documents three additional shifts, along with paid childcare during those hours. The update would identify the additional dates and attach the wage and childcare records separately. Those documents explain the request; they do not establish that every amount is payable under the claim.
Submit the update through the channel the insurer identifies, and retain a copy of exactly what you sent. Ask for confirmation of receipt and whether any attachment is missing or unreadable. After a telephone conversation, a brief written follow-up can record the questions discussed and any next steps described by the adjuster.
If the file appears unchanged after submission, ask which issue remains unresolved: receipt of documents, review of an amount, or a coverage question. Understanding delays between claim review stages can help you frame a more specific status request. Do not assume that confirmation of receipt also means the insurer has accepted the new information or approved payment.
Keep the amount of the documented loss separate from the amount potentially available under insurance. Ask which coverage is being considered, what limits apply, and whether any part of the request is disputed or excluded. Additional documentation does not itself increase a policy limit, so a more complete claim can still leave a household with unpaid expenses.
If an expense is not being paid, ask for the reason in writing rather than treating every unpaid amount as the same problem. Missing documentation, a disputed charge, and an applicable coverage limit raise different questions. Before relying on another policy as a possible payment source, ask whether it applies to the particular expense and circumstances.
Clarify What Any Payment Would Resolve
Before accepting a proposed payment or signing accompanying paperwork, ask exactly which expenses and claim issues it addresses. Do not assume the payment is only an interim step or that later expenses can automatically be added. Request clarification about any release language and whether the proposed agreement would resolve claims beyond the amounts currently listed.
Compare the proposal with your expense record, including outstanding balances and amounts still under review. Keep uncertain future costs clearly separate from bills already received. If there is a gap between documented expenses and proposed payment, ask whether the explanation is a coverage limit, a disputed amount, or something else before evaluating the available options.
Choose One Clear Next Step
A practical next step is to prepare a short status sheet showing what you submitted, what the insurer acknowledged, and which questions remain unanswered. Use it to request a focused written response rather than resending the entire file without explanation. Clear records cannot remove a coverage limit, but they can help your family distinguish confirmed information from assumptions before making financial decisions.
Additional Bicycle Accidents Articles
How Insurers Evaluate Pain and Suffering in Bicycle Accident Claims
Pain and suffering is harder to document than a repair bill. Specific examples of daily limitations, honest records of changes, and consistent supporting documents help explain a bicycle crash’s personal impact.
Lost Wages When Light Sensitivity After a Bicycle Injury Limits Screen Work
Job duties, written restrictions, schedules, and pay records can explain a loss of screen-based work. Separate documented wage losses from unresolved questions about the crash.
Unresolved Fault Questions Can Delay Charlotte Bicycle Accident Claims
A disputed account of a bicycle crash can leave a claim waiting on evidence or a responsibility decision. Clear records help distinguish what is missing from what remains contested.